VWAP Trading Strategy: How Volume-Weighted Price Works
In this article

Volume-weighted average price (VWAP) is an intraday technical indicator that measures the average price of an asset based on both price and trading volume across a single session. Unlike standard moving averages, it gives greater statistical weight to high-volume price levels, providing traders with an execution benchmark to gauge market value. Because it resets daily at session open, standard unanchored VWAP is used exclusively for short-term intraday market analysis.
Volume-weighted average price (VWAP) is an intraday technical benchmark that calculates the average price of an asset using both price and trading volume. Unlike a standard moving average, VWAP gives greater weight to price levels where more trading activity has occurred.
Retail traders exploring a VWAP trading strategy may use the indicator to assess relative value, identify intraday market direction and evaluate execution quality within a single trading session. This guide explains how the volume-weighted benchmark works, common intraday setups, how it differs from traditional moving averages and the practical execution risks CFD traders need to consider.
Quick Takeaways
- VWAP combines intraday price and volume into a single cumulative benchmark that resets at the start of each trading session.
- Institutional traders may use VWAP as an execution benchmark when assessing whether orders have been filled above or below the session's volume-weighted average price.
- Standard deviation bands above and below the VWAP line can help traders assess when price has moved significantly away from the session average.
- Retail CFD traders need to consider differences in volume data, as broker tick volume may differ from the underlying exchange volume.
What Is the VWAP Indicator and How Does It Work?
The volume-weighted average price indicator calculates a cumulative average price based on the total trading volume recorded throughout the trading day. In institutional technical analysis, price and volume relationships can provide a useful reference for assessing execution, as discussed by the CFA Institute.
To calculate VWAP, trading platforms take the typical price for each period and multiply it by the volume traded during that interval:
Typical Price = (High + Low + Close) / 3
VWAP = Cumulative (Typical Price * Volume) / Cumulative Volume
Because VWAP uses cumulative data, the calculation begins again at the start of each trading session. This daily reset — where the cumulative calculation starts again for each new session — means that standard unanchored VWAP is designed primarily for intraday analysis rather than multi-day swing charts.
Key Types of VWAP Trading Setups
Traders use the VWAP line in several intraday approaches. Rather than treating a touch or crossover of the line as an automatic buy or sell signal, traders can consider VWAP alongside the wider market context and other forms of confirmation.
VWAP Support and Resistance Bounces
When an asset is moving in an established intraday trend, price may retrace towards its volume-weighted average. During a bullish session, traders may view the area around VWAP as potential support or a reference for the session's average traded price. During a bearish session, the line may instead act as potential resistance.
VWAP Crossover Strategy
A crossover occurs when the current market price moves through the VWAP line. A move above VWAP means that the current price is trading above the session's volume-weighted average and may indicate strengthening upside momentum. A move below VWAP means that price is trading below the session average and may indicate increasing selling pressure.
A crossover alone does not confirm that a new trend will continue, so traders may look for additional price, volume or momentum confirmation before acting on the signal.
Standard Deviation Bands
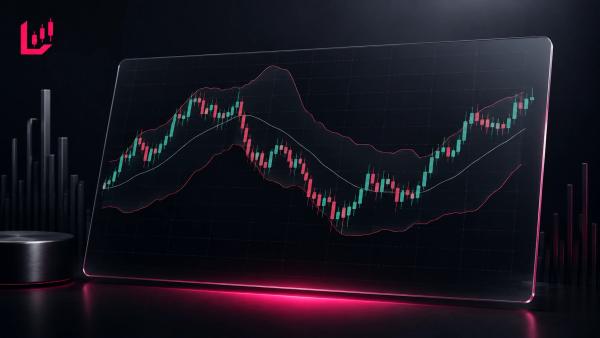
Adding standard deviation bands above and below the main VWAP line creates volatility envelopes around the session average. The upper bands show how far price has moved above VWAP, while the lower bands show extensions below it. Traders can monitor these outer bands to assess how far the current price has moved from the session's volume-weighted average.
Technical Indicators vs VWAP: How It Differs from Moving Averages
Understanding the structural differences between technical benchmarks can help traders choose a tool that suits their timeframe and analysis.
Standard technical indicators, such as a simple moving average (SMA), give each time bar equal weighting in their calculations. For example, a bar representing 100 contracts has the same influence on an SMA as a bar representing 10,000 contracts. VWAP, by contrast, gives greater weight to periods with higher trading volume.
Combining VWAP with Moving Averages
Traders may combine VWAP with moving averages to add further context when assessing market direction. For example, using a moving average crossover on a lower timeframe alongside VWAP may help traders distinguish directional moves from short-term price fluctuations during choppy, range-bound sessions. However, combining indicators does not eliminate false signals or guarantee that a price move will continue.

The Pitfalls: CFD Volume Limitations and Strategy Failure
Although volume-weighted average price is a widely used analytical tool, trading around VWAP involves specific practical risks, particularly for retail Contract for Difference (CFD) traders.
In practice, many intraday traders find that price can cross the main VWAP line repeatedly during quiet periods of consolidation. Assuming that every touch of the line will provide reliable support or resistance can lead to a series of small, repeated losses.
Exchange Volume vs CFD Tick Volume
The standard VWAP formula relies on actual trading volume from a centralised exchange. CFDs, however, are over-the-counter (OTC) derivatives. Most CFD platforms provide tick volume — the number of price updates within a given period — or broker-specific volume data rather than centralised exchange volume.
If a broker's tick volume differs from activity in the underlying centralised market, the VWAP calculated on a CFD chart may appear at a slightly different level from a benchmark calculated using exchange-traded volume.
Runaway Trend Risk and Costs
During a strong, low-volatility trend, price can remain above or below VWAP for an entire trading session without pulling back towards the line. Traders who attempt to sell an asset simply because its price has moved well above VWAP risk taking a position against a trend that continues to strengthen.
CFD trading also involves leverage, which can increase both your potential gains and losses. You should factor in trading costs too — including spreads and potential overnight fees — before committing to any strategy. According to FCA-mandated risk disclosures, 74–89% of retail CFD accounts lose money, largely due to unmanaged risk, excessive leverage or a failure to account for execution costs.
Conclusion: How to Use a VWAP Trading Strategy
A VWAP trading strategy provides a way to assess intraday price in relation to trading volume. Traders may use the benchmark to evaluate market participation, assess short-term momentum or compare an execution price with the session's volume-weighted average. VWAP is generally more useful when considered alongside broader trend analysis and clearly defined risk controls.
No technical indicator can provide guaranteed trading signals. If you trade CFDs, make sure you understand the source and limitations of volume data on your platform, and manage your position size carefully. For a more detailed overview of different market approaches, explore our CFD trading strategies hub. Trading CFDs carries a high level of risk because of leverage, so traders should test strategy concepts on a demo account before committing capital.
Traders who want to build a consistent vwap trading strategy should also test their approach on a demo account before applying it live.
FAQ
What is the main purpose of a VWAP trading strategy?
A VWAP trading strategy uses the volume-weighted average price line as an intraday benchmark to determine whether an asset is trading above or below its session average value. Institutional market participants use it as an execution target to minimise market impact when filling large orders, while retail traders monitor it for potential support, resistance, or momentum continuation signals.
Is VWAP better than a simple moving average (SMA)?
VWAP is not strictly superior to a simple moving average, but it serves a different analytical purpose. While a simple moving average assigns equal weight to every price bar regardless of activity, VWAP factors in trading volume to reflect true liquidity distribution. However, VWAP resets daily and applies primarily to intraday timeframes, whereas SMAs can be used continuously across multi-day and multi-week charts.
Can you use VWAP for swing trading across multiple days?
Standard unanchored VWAP resets at the start of every trading session, making it unsuitable for standard multi-day swing trading charts. Applying a standard intraday VWAP to a daily or weekly chart creates distorted calculations. Swing traders who wish to incorporate volume weighting over longer periods must use an Anchored VWAP (AVWAP), which allows the calculation to start from a specific historical event or date.
How do standard deviation bands work with VWAP?
Standard deviation bands are plotted above and below the central VWAP line to mark statistical volatility envelopes. The first and second deviation bands represent price extensions relative to session volume. Traders use these outer bands to identify conditions where price has stretched far away from the session average, signalling potential mean-reversion setups or strong breakout momentum.
Why can VWAP readings differ on retail CFD platforms?
Centralised exchange markets report total contract volume, which feeds the precise VWAP calculation. Contracts for difference (CFDs) are over-the-counter derivatives where platforms may use tick volume (price frequency updates) or broker-proprietary liquidity feeds. If tick volume diverges from centralised market activity, the resulting VWAP line on a retail chart may sit at a slightly different price level than the underlying exchange benchmark.