What Is an Iceberg Order? How Sliced Orders Work
In this article

An iceberg order is a large limit order split into a small visible display size and a larger hidden reserve quantity. By masking the full trade volume on public order books, it allows institutional market participants to execute large block orders while minimising market impact and front-running risks.
Find out what is an iceberg order and how institutional traders split large block orders into visible display slices and hidden reserves.
An iceberg order is a large limit order divided into smaller quantities, with only part of the total order displayed publicly to conceal its full size from the order book.
Institutional traders and other market participants use iceberg orders to execute large-volume orders without revealing their full trading intent to the wider market. This can help reduce the risk of moving the market price before the entire order is filled.
Quick Takeaways
- Iceberg orders divide a large limit order into a visible display slice and a hidden reserve quantity on Level 2 market depth.
- When the visible slice is fully filled, the exchange matching engine automatically releases another portion of the hidden reserve at the same limit price.
- Replenished display slices lose their original time priority and move behind existing visible orders at that price level.
- Iceberg orders can reduce market impact, but they do not guarantee full execution if the market moves beyond the specified limit price.
What Is an Iceberg Order in Trading?
In simple terms, the iceberg order meaning comes down to one idea: only a small visible slice ever reaches the public order book.
An iceberg order, also known as a reserve order or sliced order, takes its name from a physical iceberg, where only a small part of the total structure is visible above the surface.
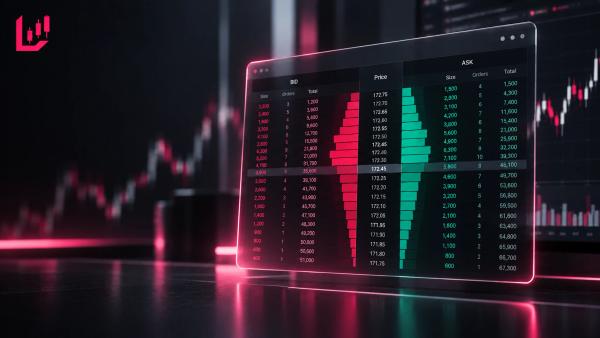
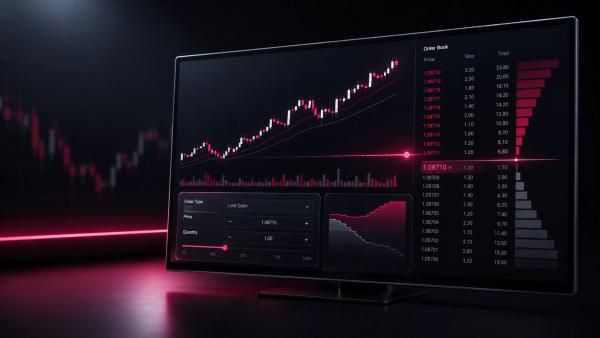
In financial markets, the visible "tip" represents the display size shown on Level 2 market data or Depth of Market (DOM) screens. The "submerged" portion is the hidden reserve volume held within the exchange's matching engine.
Order Book Layer | Visibility Level | Example Volume Breakdown |
|---|---|---|
Display Slice (Visible Tip) | Published to public Level 2 / DOM order books | 10 Lots @ 1.0850 |
Reserve Queue (Submerged Volume) | Hidden inside the exchange matching engine | 290 Lots @ 1.0850 (split in reserve) |
Total Iceberg Order Size | Full position size managed by trader | 300 Lots Total |
When institutional investors need to enter or exit large positions, placing one very large market or standard limit order can create an obvious imbalance in publicly visible liquidity. Other market participants may notice the size and adjust their quotes, potentially moving the price away before the full order is executed.
By dividing the total volume into a sequence of smaller displayed slices, an iceberg order reduces how much of the underlying supply or demand is visible at any one time.
How Iceberg Orders Work in Execution
Iceberg orders follow an automated, repeating execution process managed by exchange matching engines or Electronic Communication Networks (ECNs).
In plain terms, the matching engine is just the exchange's system for lining up who trades with whom — and iceberg orders quietly slip to the back of that line each time a new slice appears.
- Order Submission: The trader specifies two main parameters: the total order quantity, for example 500 lots, and the maximum display size, such as 20 lots.
- Initial Display: The exchange algorithm places the visible 20-lot slice on the order book at the chosen limit price. The remaining 480 lots stay in the hidden reserve queue.
- Execution & Replenishment: Opposing market orders trade against the visible 20-lot slice. Once that slice is fully filled, the algorithm automatically takes another 20 lots from the reserve and publishes them as a new visible slice.
- Queue Priority Adjustment: According to exchange execution specifications published by CME Group, reserve quantities retain the same limit price but lose their time priority when replenished. Each newly displayed slice therefore moves behind existing visible orders already waiting at that price level.
This process continues until the full 500-lot order has been executed or cancelled, or until the market price moves beyond the specified limit level. Once you have the iceberg order explained this way, the mechanics of display slices and hidden reserves become much easier to follow.
Iceberg Orders vs Standard Limit Orders
Traders researching what is an iceberg order often start by comparing it against a standard limit order first.
A standard limit order displays 100% of its size on the order book and maintains price and time priority for the full visible quantity. An iceberg order reduces visibility but gives up time priority on replenished reserve quantities.
Execution Parameter | Standard Limit Order | Iceberg Order |
|---|---|---|
Market Book Visibility | 100% of the order volume is visible on Level 2 / DOM | Only the specified display slice is visible |
Market Impact | Can be high for large-volume orders and may influence price | Reduced by concealing the full order size |
Queue Time Priority | Retains its original queue position for the full visible volume | Replenished slices move to the back of the queue |
Execution Latency Risk | Lower fill delay if price remains at the specified level | Higher potential fill delay because queue priority is repeatedly lost |
Strategic Advantages and Execution Risks
So what does iceberg order mean in day-to-day execution? It means a trader's true position size stays concealed until the order is fully filled.
In practice, many institutional traders find that order slicing can help reduce market disruption when executing large positions, although it introduces execution trade-offs when market conditions become volatile.
Primary Advantages
- Reduced Market Impact: Concealing a large proportion of the order can make it harder for other market participants to adjust bid or ask prices in response to the full trade size before execution is complete.
- Protection Against Algorithmic Front-Running: High-frequency trading (HFT) algorithms monitor market depth for large block orders. Iceberg slicing can make institutional trading intent more difficult to detect.
- Controlled Liquidity Exposure: Traders can test available counterparty liquidity at specific price levels without displaying their full order size.
Primary Risks
- Queue Priority Loss: Each newly displayed slice is treated as a new order entry, so existing standard limit orders at the same price take priority. In slower markets, this can increase the time required to fill the entire order.
- Partial Fill Risk: If the market moves quickly away from the limit price after only a few slices have been filled, the remaining reserve quantity may stay unexecuted. Traders who require immediate full execution may instead consider conditional order structures such as a fill or kill order, rather than a sliced limit order.
- Algorithmic Detection: Modern order-flow algorithms can monitor repeated replenishment at the same price level. Specialised software may identify iceberg activity in real time, reducing some of the intended concealment benefit.
Conclusion
To summarise what is an iceberg order in practice: it is an execution tool that hides the true size of a large position from the public order book.
Iceberg orders provide a structured way for institutional traders to execute large-volume orders while limiting how much of the total quantity appears on the public order book. By combining visible display slices with hidden reserve volume, traders can reduce potential market impact, although replenished quantities give up time priority.
Understanding how iceberg orders work alongside other order types can help traders better assess how liquidity and execution operate beyond the visible market depth.
When trading leveraged instruments such as Contracts for Difference (CFDs), factors including execution speed, slippage and available liquidity can affect order fills. According to data published by the UK Financial Conduct Authority (FCA), between 70% and 80% of retail investor accounts lose money when trading CFDs, reflecting the impact of leverage and rapid price volatility.
Order execution mechanics should therefore be treated as part of a broader educational understanding of trading risk rather than as a way to guarantee better results.
FAQ
What is the main purpose of an iceberg order?
The primary purpose of an iceberg order is to execute large trading volumes without disrupting market prices or revealing institutional entry points on Level 2 order books.
Does an iceberg order guarantee zero slippage?
No. Iceberg orders manage market impact, but they do not guarantee complete fills or zero slippage if liquidity thins or prices move past the limit threshold.
What is the visible portion of an iceberg order called?
The public portion displayed on the order book is called the display size or display slice, while the remaining volume sits in the hidden reserve queue.
Why do replenished iceberg slices lose time priority?
Matching engines treat each newly surfaced display slice as a new order entry, moving it behind existing visible orders at that specific price level.
Can modern trading algorithms detect hidden iceberg orders?
Yes. Specialised tape-reading and high-frequency trading algorithms identify iceberg orders by monitoring rapid volume replenishment at single price levels.